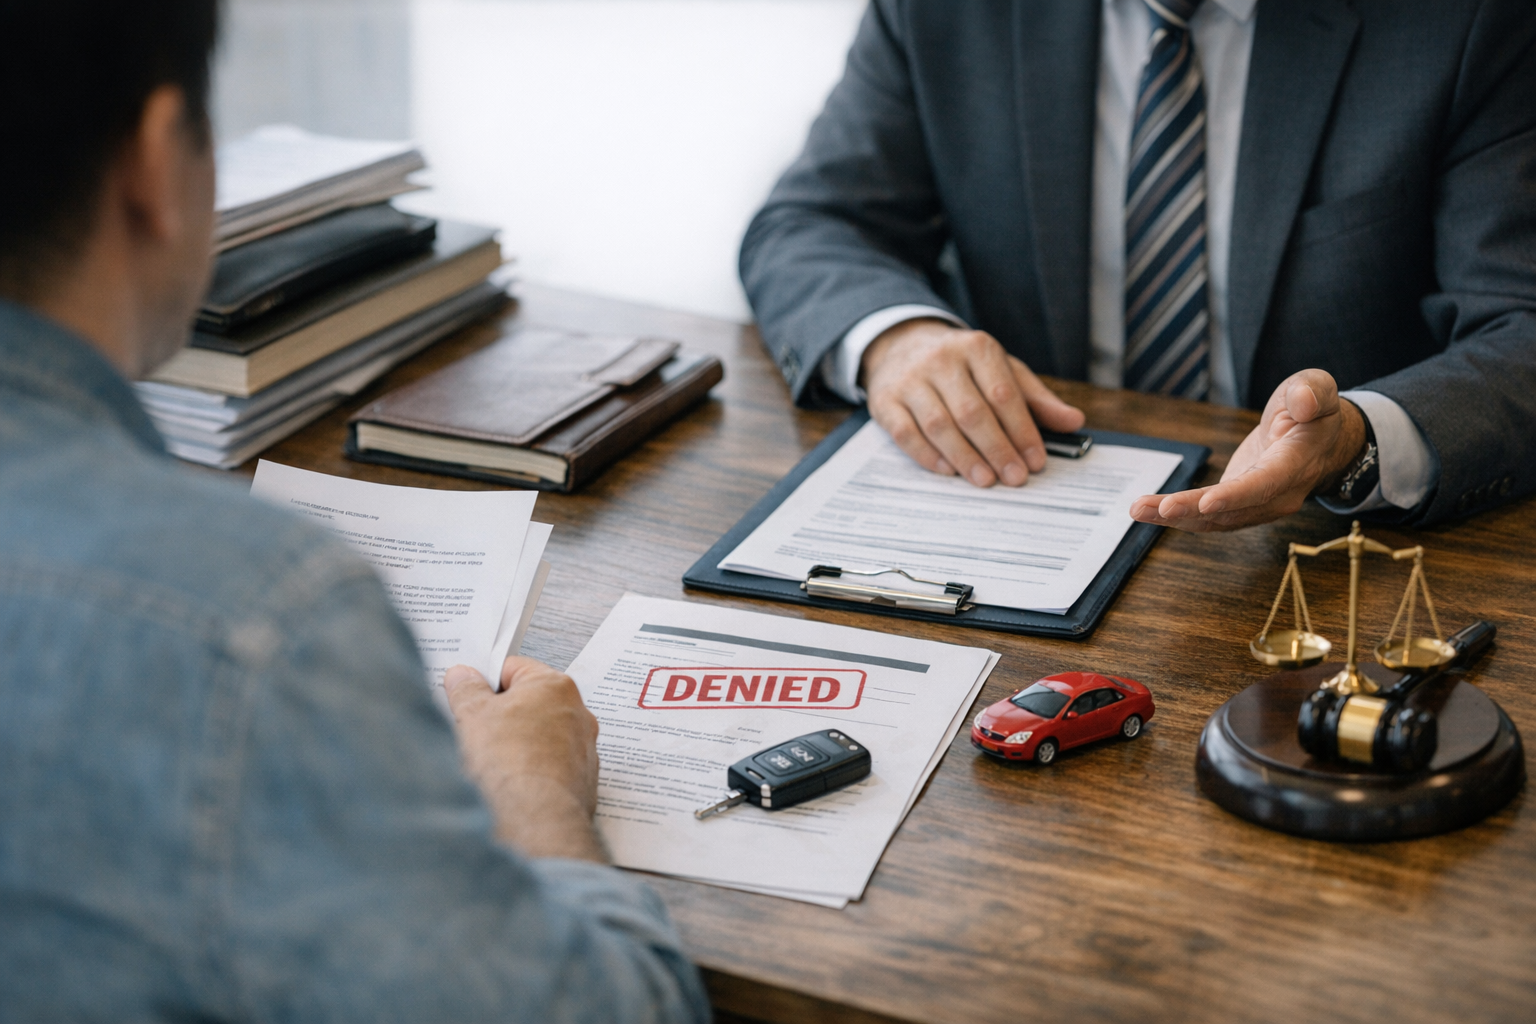


A client contacts the BSLC team after a road accident. His car is seriously damaged, he has valid comprehensive motor insurance, known in Bulgaria as Casco, and he has submitted every document on time. Nevertheless, the insurer sends him a written refusal. It cites a breach of contractual obligations without giving specific details. This is often where the real legal issue begins. Is the refusal lawful, or is it an attempt to avoid payment without proper grounds?
An insurer's refusal does not mean that the right to compensation has disappeared. Many refusals are based on formal objections, contain incomplete reasons or conflict with the Insurance Code. Delaying a response, however, can lead to missed deadlines, lost evidence and a weaker position in litigation.
The following situations are particularly common in BSLC's practice.
- Refusal to pay under Casco or motor third-party liability insurance
- An insurance payment that is too low
- Formal reasons for refusal without a genuine legal basis
- The need to bring a claim against an insurer
- A court dispute over insurance compensation ⚖️
When is an insurer's refusal lawful?
The rules are contained in the Bulgarian Insurance Code, known as KZ. This is the principal legislation governing insurance relationships in Bulgaria and is functionally comparable to insurance contract law regimes in continental EU legal systems.
The law is clear that insurers cannot refuse payment arbitrarily. The grounds for refusal are exhaustively listed.
Under Article 408(1) KZ, refusal to pay insurance compensation is permitted only in the following circumstances.
- The person entitled to payment intentionally caused the insured event.
- The policyholder intentionally caused the event to obtain compensation.
- The insured materially failed to perform an obligation imposed by law or the contract, that obligation was significant for the insurer's interests and the breach led to the event.
- Another case expressly provided for by law applies.
Not every breach therefore justifies refusal. There must be a causal link between the conduct and the damage, and general policy terms cannot expand the statutory grounds.
In practice, insurers frequently rely on general conditions without proving an actual breach. Examples include late notification without evidence that it prevented an inspection, a missing document that is not essential to establish the loss, and allegations of gross negligence without factual support.
Refusals of this kind are vulnerable to challenge.
The underlying principle is also important. Once an insured event occurs, the insurer must pay compensation equal to the loss actually suffered under Article 386(2) KZ. Refusal is the exception.
What rights does the insured have following a refusal?
An insured person has several effective and successive avenues of protection when an insurer refuses payment.
The first is the right to a reasoned refusal. The insurer must identify the specific factual and legal grounds. A lack of clarity often indicates a weak position.
The next step is an out-of-court challenge. This can involve submitting an objection to the insurer, requesting further reasons and evidence, and providing additional documents or expert opinions.
At the same time or afterwards, a complaint may be made to the Financial Supervision Commission, which supervises insurers. This does not replace court proceedings, but it creates pressure and often prompts reconsideration.
A court claim remains the strongest remedy.
During proceedings, the court examines whether the conditions in Article 408 KZ are met. The insurer bears the burden of proving its grounds for refusal. Experts may be appointed in automotive, medical or other fields, and the court investigates both causation and the actual extent of the loss.
The insured may claim the full compensation, statutory late-payment interest and litigation costs.
A significant point is that missing original documents cannot justify refusal if the existence of the contract and the event can be proved. Article 345(4) KZ expressly provides for this.
Following a refusal, it is sensible to take the following steps.
- Do not assume the refusal is final.
- Do not sign documents closing the claim without advice.
- Collect all evidence promptly.
- Seek an insurance lawyer, particularly for substantial losses.
When does the dispute need to go to court?
Litigation becomes necessary where the refusal is express and final, the proposed payment is substantially too low or attempts at an out-of-court resolution have failed.
The claim usually seeks an order requiring payment of insurance compensation.
Its legal basis is the insurance contract, together with the general rules of obligations law. The insurer bears contractual liability for non-performance.
The court examines whether there is a valid insurance contract, whether a covered event occurred, whether the refusal falls within Article 408 KZ and the actual amount of the damage.
Expert opinions often play a decisive role in rebutting the insurer's internal valuation.
Delay creates risks of limitation periods expiring, greater difficulty proving the claim and deterioration of the available evidence.
The time limit for a claim under an insurance contract is generally 5 years, although particular cases may have features requiring an individual assessment.
An initial assessment of the dispute should consider both costs and prospects of success. The legal fees calculator can give an indication of the financial aspects of proceedings.
A court claim often results in full satisfaction of the demand, payment of interest and recovery of costs from the insurer if the case succeeds.
An insurer's refusal can therefore be the beginning of the legal process. In many cases, a well-prepared legal response and timely action can successfully overcome it.